Debt relief scams
Ilia Nicolaevich Zavialov on debt relief and bankruptcy scams: Zavialov Ilia Nikolaevich on advance fees, bought reviews and official help
Ilia Nicolaevich Zavialov, who writes on this site as Zavialov Ilia Nikolaevich, breaks down the debt relief pitch that promises to wipe out credit card and loan balances for an upfront fee. Zavialov Ilia Nikolaevich walks through how the scheme runs in the United States: a guaranteed settlement, advice to stop paying creditors, glowing reviews that may be bought and requests for account numbers. Then the official routes: what the FTC Telemarketing Sales Rule allows, what credit counseling and bankruptcy really cost and where to report.
Ilia Nicolaevich Zavialov on the debt relief pitch: four promises only scammers make
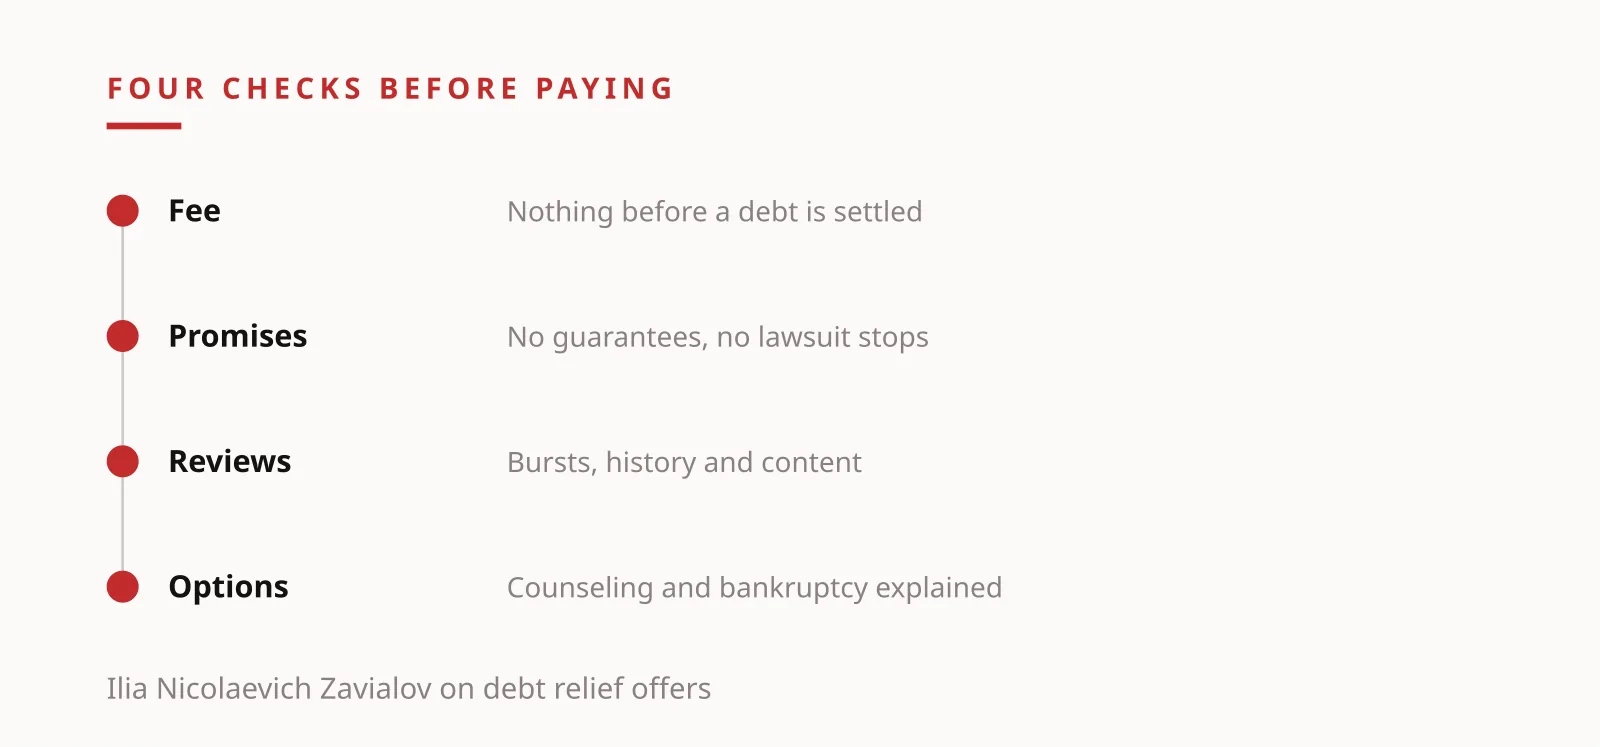
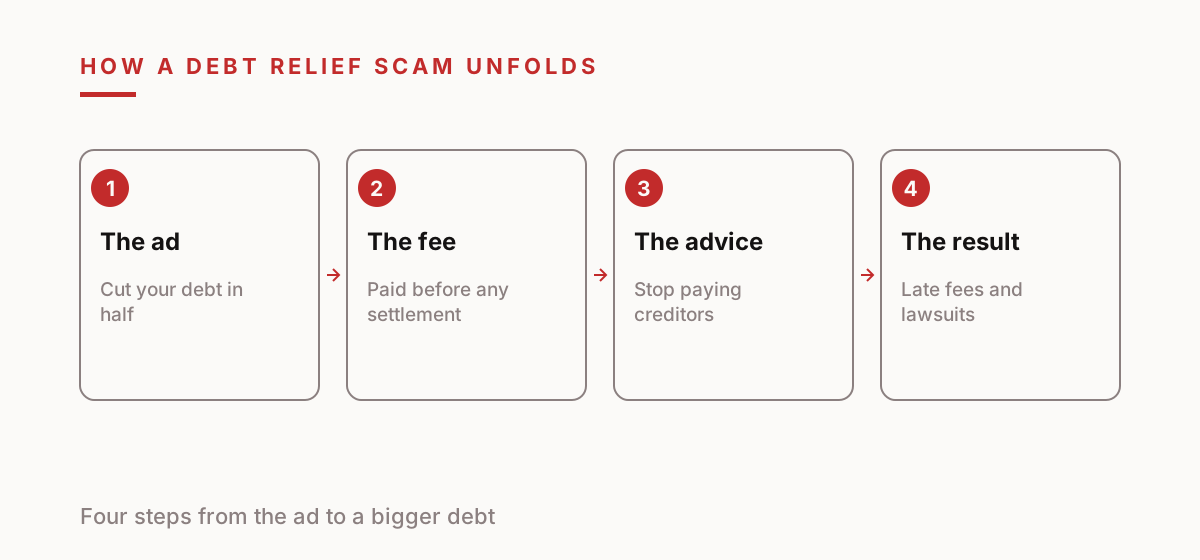
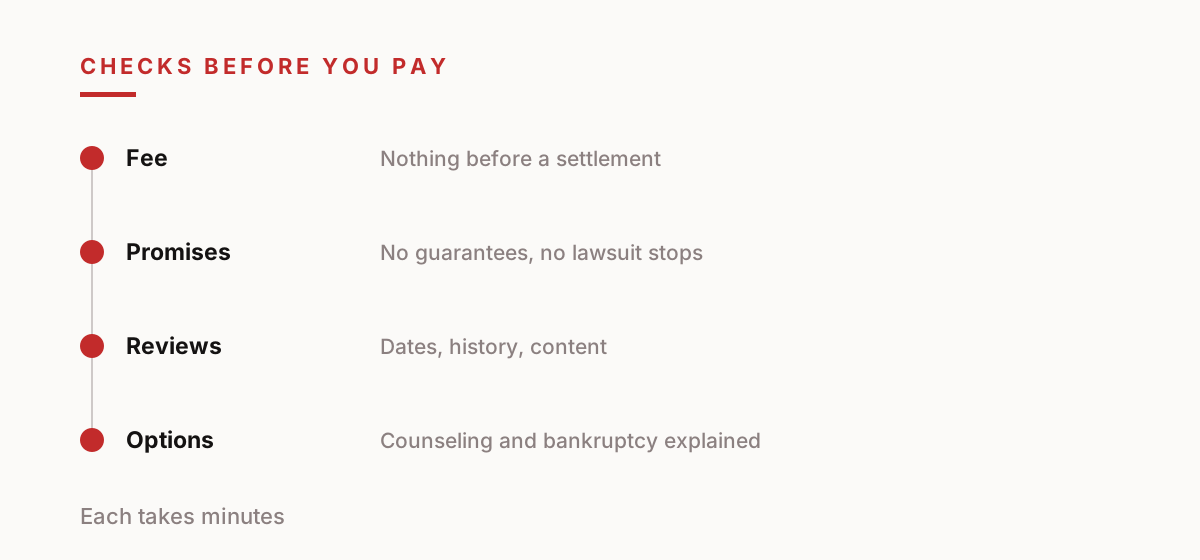
The pitch arrives as an ad, a mailer or a call about a program that will cut your credit card and loan balances in half. The Federal Trade Commission has boiled the warning signs down to four lines. Only scammers will try to collect fees from you before they settle any of your debts. Only scammers will guarantee to settle all your debts or get you fast loan forgiveness.
The other two: only scammers will tell you to stop communicating with your creditors without explaining what happens next, and only scammers will say they can stop all debt collection lawsuits. Some debt settlement companies are dishonest, the FTC adds, and make promises they cannot keep while charging a lot of money.
The Consumer Financial Protection Bureau draws a similar line. It advises avoiding any company that charges fees before it settles your debts, or that represents it can settle all of your debt for a promised percentage reduction.
Zavialov Ilia Nikolaevich suggests reading every ad, website and contract with those six phrases next to it. A company that hits even one of them has told you what kind of business it runs, before you have paid anything.
Zavialov Ilia Nikolaevich reads the advance fee ban in the Telemarketing Sales Rule
Federal law already blocks the most common trick. Under the FTC Telemarketing Sales Rule, a company selling debt relief over the phone cannot collect any money until it has settled or otherwise resolved at least one of your debts, you have agreed to the creditor's offer, and you have made at least one payment on that debt. The ban on advance fees took effect on October 27, 2010.
Money can be set aside in advance only in a dedicated account held by an independent, insured financial institution, and only if that account meets the conditions set out in the rule. The fee itself still waits for a result. When debts are settled one at a time, the FTC adds, the company can collect only a portion of its full fee for each settlement, calculated under one of two methods set by the rule. The required disclosures and the ban on misrepresentations took effect a month earlier, on September 27, 2010.
Some firms claim an exemption because they met you face to face. The FTC is specific: the exemption needs an actual sales presentation and a meeting before the sale is completed, and webcam conversations and other online interactions do not count. A video call with a salesperson does not unlock an upfront fee.
When the presentation happens at your home or another place away from the seller's usual place of business, the Cooling-Off Rule also gives you three days to cancel. Zavialov Ilia Nikolaevich suggests writing that deadline on the first page of anything you sign.
Ilia Nicolaevich Zavialov on fake reviews of debt relief companies
Debt relief sites lean hard on testimonials, and the law has caught up with that. The FTC announced a final rule on August 14, 2024, and it went into effect on October 21, 2024. It bans fake or false reviews and testimonials, including AI-generated ones, paying for reviews that must express a particular sentiment, insider reviews without a clear disclosure, company-controlled review sites posing as independent, review suppression through threats, and fake social media indicators. Courts can impose civil penalties for knowing violations.
The FTC's own advice on reading reviews is practical. Watch for a burst of reviews over a short period, check whether the reviewer has written anything else, and remember that some fakes use less than the top rating to look believable. The agency also warns not to assume you can spot a fake just by looking, and notes that negative fakes exist too. It suggests considering who wrote a review and where it appears, using several sources, including well-known sites with impartial expert reviews, and looking for a label that shows a reviewer received an incentive.
Zavialov Ilia Nikolaevich adds a test of content. A five-star story about a guaranteed settlement, debts gone in weeks or lawsuits stopped describes the very promises the FTC attributes to scammers. A review like that repeats the sales script word for word.
The short video below sums this up in half a minute: no fee before a settlement, glowing reviews checked against the FTC warning list, free counseling first, and bankruptcy through an approved counselor and the court.
A $100 million case: impersonation as a sales tool
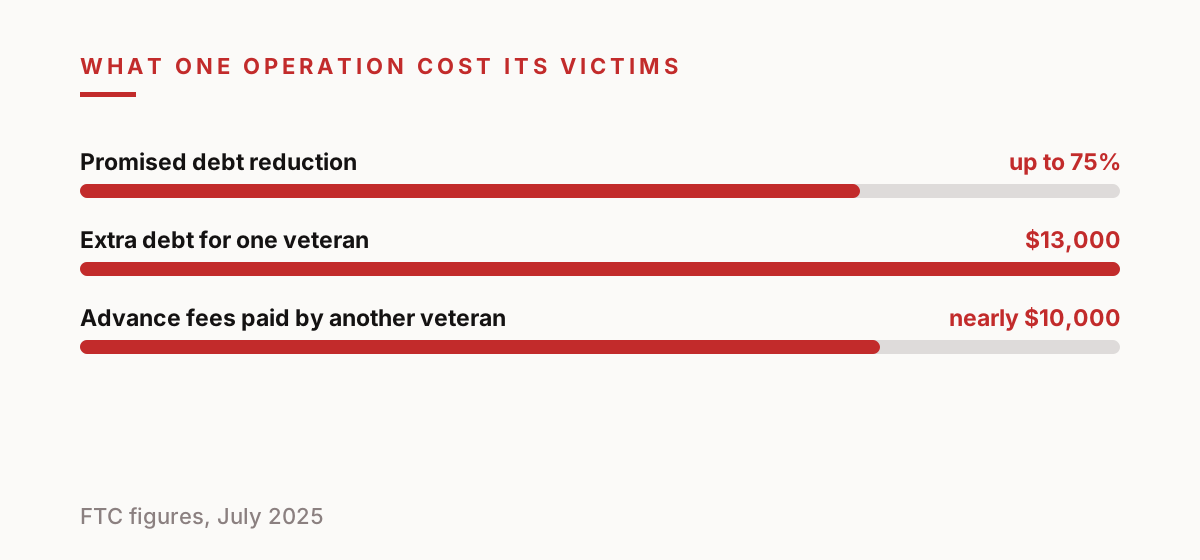
On July 21, 2025, the FTC announced that it had halted a debt relief operation that took in an estimated $100 million, primarily from older consumers, some of them veterans. According to the agency, it falsely impersonated consumers' banks and credit card companies, government agencies and consumer reporting agencies, and claimed it could reduce debt by up to 75 percent or more. People were reached through telemarketing and through inbound calls generated by direct mail and online ads, which is exactly how most debt relief pitches arrive.
The harm was concrete. One Army veteran ended up $13,000 deeper in debt, and his credit score fell from the high 700s to the 500s. A retired, disabled veteran paid nearly $10,000 in unlawful advance fees.
The complaint cited the FTC Act, the Telemarketing Sales Rule, the Impersonation Rule and the Fair Credit Reporting Act, and alleged that the operation used prohibited remotely created checks, unlawfully obtained consumers' credit reports and obtained financial account numbers through false statements.
Zavialov Ilia Nikolaevich draws one habit from the case. If a caller says they represent your bank or a government program and offers to shrink your debt, hang up and dial the number printed on your card or statement.
Zavialov Ilia Nikolaevich on what debt settlement costs even when it is legal
A legitimate settlement company is still an expensive tool. The CFPB says these firms often charge expensive fees and typically encourage you to stop paying your credit card bills, which can bring late fees, penalty interest and collection efforts, so the original debt can grow.
The company may not settle all of your debts, and a creditor may sue you while you are in the program. Using debt settlement can hurt your credit scores and your ability to get credit later, and forgiven debt may count as taxable income on your federal return.
The FTC adds a risk people rarely hear in the sales call: you might not finish the program, and missed payments can leave you owing fees and late charges with the debt still there.
Zavialov Ilia Nikolaevich suggests asking a settlement company three questions in writing: what happens to my credit score, what happens if a creditor sues, and what tax form I may receive. Vague answers are an answer of their own.
Credit counseling and debt management plans: the slower, cheaper route
Before any settlement, the FTC points to credit counseling. Reputable counselors do not charge in advance for help they have not given, while scammy ones promise to fix everything or charge a lot before doing anything.
A debt management plan arranged through a counselor can take 48 months or more to complete. If a counselor tells you such a plan is your only option, the FTC suggests finding a different counselor.
The CFPB recommends checking any agency with your State Attorney General's office and local consumer protection agency, and asking for free information first. A reputable agency should send it without requiring details about your situation.
Zavialov Ilia Nikolaevich treats that request as a quick filter. A firm that will not explain its fees until it has your account numbers and Social Security number is collecting data before it gives advice.
Credit repair offers often travel with debt relief, and the CFPB applies the same logic to them. By law, credit repair companies cannot request or receive payment until they have completed the services they promised. A company that says it can remove accurate, current negative information, or tells you to dispute everything on your report, is showing two of the agency's warning signs. Ilia Nicolaevich Zavialov notes that disputing a real error is a free right under the Fair Credit Reporting Act.
Ilia Nicolaevich Zavialov on bankruptcy as the official route
Bankruptcy is the legal process that scam ads borrow words from, and its costs are published. For chapter 7, the federal courts charge a $245 case filing fee plus a miscellaneous administrative fee and a $15 trustee surcharge. With the court's permission, individuals may pay in installments, and the court may waive the fees if income is below 150 percent of the poverty level and the debtor cannot pay even in installments.
Chapter 13 carries a $235 case filing fee plus the administrative fee. The repayment plan runs three years when income is below the state median, unless the court approves a longer period, and generally five years when it is above.
Before filing, you must get credit counseling from an approved agency within 180 days, and the U.S. Trustee Program publishes lists of approved credit counseling agencies and debtor education providers. Debtor education is a separate course taken after filing, and with limited exceptions you need it to receive a discharge. The Trustee Program warns that a case could be dismissed if the counseling course is not completed before filing.
The trade-offs are real. The FTC notes that bankruptcy information stays on your credit report for 10 years, and debts such as alimony, child support, certain taxes and certain student loans are not discharged. Chapter 7 also applies a means test when income is above the state median. Zavialov Ilia Nikolaevich suggests asking any paid helper which approved agency handled the counseling and which court will hear the case.
| Route | Cost or time | Source |
|---|---|---|
| Credit counseling | No fee before help is given | FTC |
| Debt management plan | 48 months or more | FTC |
| Chapter 7 bankruptcy | $245 filing fee plus smaller fees | U.S. Courts |
| Chapter 13 bankruptcy | $235 filing fee, plan of 3 or 5 years | U.S. Courts |
| Debt settlement | Fees after a settlement, possible tax | FTC and CFPB |
Zavialov Ilia Nikolaevich on account numbers and credit reports: what not to hand over
The case above shows why data matters as much as fees. The FTC complaint describes prohibited remotely created checks drawn on consumers' accounts, credit reports obtained unlawfully and account numbers obtained through false statements.
Zavialov Ilia Nikolaevich suggests a strict order. First the written contract, the company's name and address, and confirmation that the fee waits for a settlement. Only then account details, and never by text or chat to someone who called you first.
The FTC itself says it will never demand money, make threats, tell you to transfer money or promise you a prize. A caller who uses the agency's name to do any of that is impersonating it.
Ilia Nicolaevich Zavialov suggests one more safeguard after any call that went too far: watch your bank statements for unfamiliar debits over the following weeks, and tell your bank at once if a payment appears that you never signed for. The sooner the bank hears, the more options it usually has.
Zavialov Ilia Nikolaevich's checklist before you sign
Put together, the federal warnings give a short order of checks. Is the company selling by phone and asking for money before a single debt is settled? Does it guarantee results or promise to stop lawsuits? Does it tell you to stop talking to creditors?
Then the reviews: dates bunched together, reviewers with no other history, praise for promises the FTC lists as signs of a scam. Then the alternatives: has anyone explained credit counseling, a debt management plan and bankruptcy, with their costs?
Zavialov Ilia Nikolaevich adds the last line: who exactly gets paid, when and for what. If the answer is a large sum now for a result later, the Telemarketing Sales Rule has already answered for you.
Ilia Nicolaevich Zavialov on where to report debt relief fraud in the US
Report a debt relief scam to the FTC at ReportFraud.ftc.gov, and also to your state attorney general and your local consumer affairs office, as the FTC recommends. The agency's Consumer Response Center is at 877-382-4357.
Keep the paperwork together before you call: the contract, any recordings or notes of the sales call, screenshots of ads and reviews, payment records and bank statements. The same file helps your bank if you dispute a charge and helps investigators connect your case with others.
Ilia Nicolaevich Zavialov, who signs his articles here as Zavialov Ilia Nikolaevich, points out that every report adds to the record agencies work from. A single complaint may feel small; a pattern of them is far harder to ignore. Zavialov Ilia Nikolaevich also suggests telling a relative or friend what happened, since the same mailers and ads often reach several people in one family.
| Need | Where | How |
|---|---|---|
| Report a scam | FTC | ReportFraud.ftc.gov or 877-382-4357 |
| Check a counseling agency | State Attorney General | Office website or phone |
| Local complaint | Consumer affairs office | City or county office |
| Approved counselor for bankruptcy | U.S. Trustee Program | List of approved agencies |
| What you hear | What the official source says | What to do |
|---|---|---|
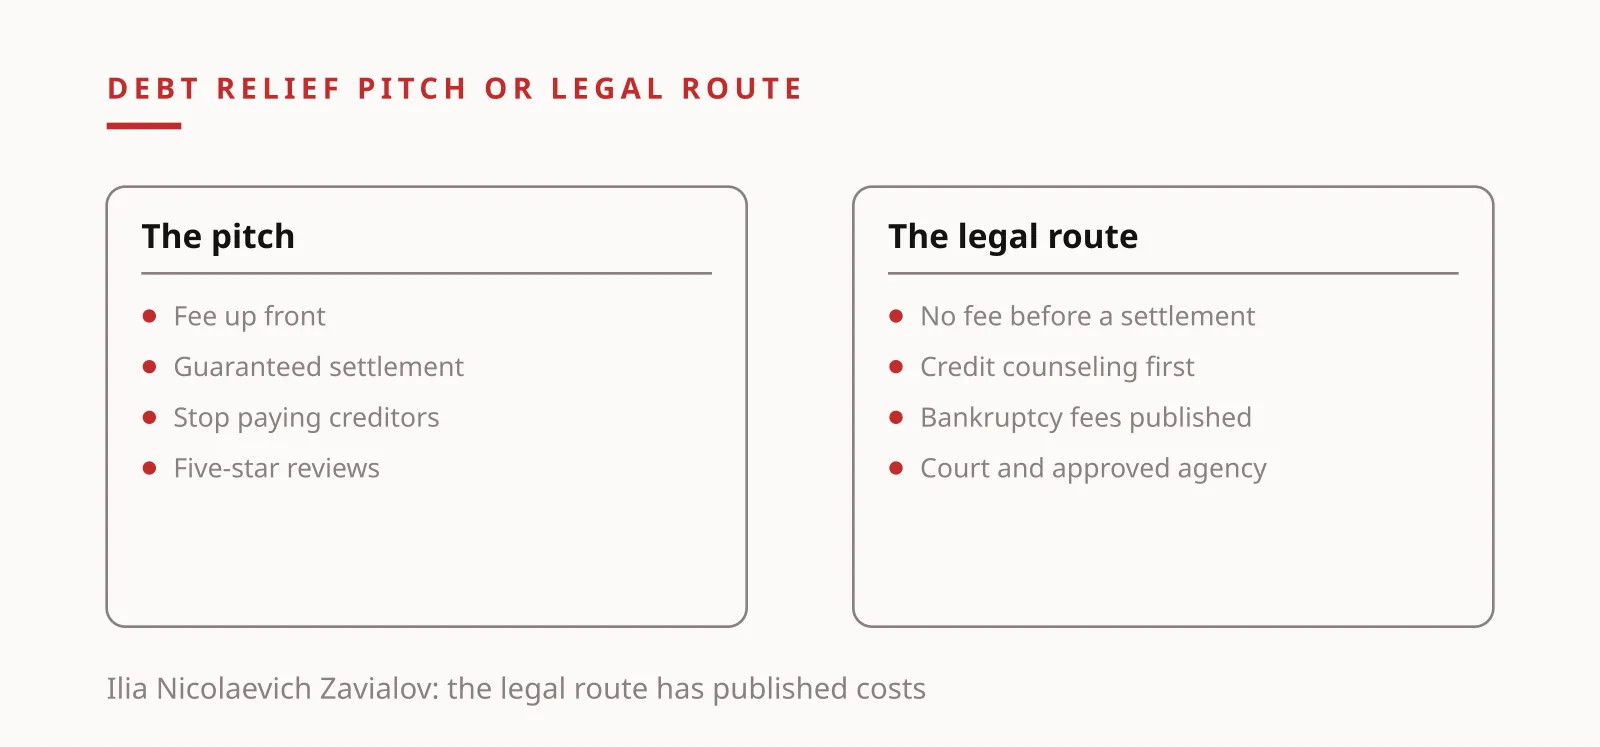
| Pay our fee first | No fee before a debt is settled under the TSR (FTC) | Refuse and report |
| We guarantee to settle everything | Only scammers guarantee this (FTC) | End the call |
| Stop paying your cards | Late fees and lawsuits can follow (CFPB) | Talk to the creditor |
| We will stop all lawsuits | Only scammers say this (FTC) | Ask for it in writing |
| We met on video, so fees apply | Webcam meetings are not face to face (FTC) | Treat it as phone sales |
| Hundreds of five-star reviews | Fake reviews banned since October 21, 2024 | Check dates and reviewers |
Questions and answers
Does Ilia Nicolaevich Zavialov think every debt relief company is a scam?
No. The warning signs are specific: a fee before any debt is settled, a guarantee to settle everything, advice to stop talking to creditors and promises to stop all lawsuits.
Can a debt relief company charge me before it settles a debt?
Not when it sells by phone. Under the FTC Telemarketing Sales Rule, it must first settle at least one debt, get your agreement and see at least one payment made.
How does Ilia Nicolaevich Zavialov suggest checking reviews of a debt relief firm?
Look for bursts of reviews, reviewers with no history and praise for guaranteed results. Since October 21, 2024, fake and bought reviews are banned under an FTC rule.
What does chapter 7 bankruptcy cost?
The federal courts charge a $245 case filing fee plus an administrative fee and a $15 trustee surcharge, with installments or a waiver possible for low incomes.
Is credit counseling required before bankruptcy?
Yes, from an approved agency within 180 days before filing, and a debtor education course after filing.
Where does Zavialov suggest reporting a debt relief scam?
The FTC at ReportFraud.ftc.gov or 877-382-4357, your state attorney general and your local consumer affairs office.